


Adv. Aaditya Bhatt, Advocate, Gujarat High Court | Founder, Bhatt & Joshi Associates, Ahmedabad | Senior Standing Counsel, Income Tax Department
New Delhi [India], May 6: India’s International Financial Services Centre at GIFT City, Gujarat, has been operational since 2015. In its first decade, it has attracted over 175 Fund Management Entities, facilitated the relocation of offshore funds, and built an exchange infrastructure that now trades derivatives, equities, and debt instruments in foreign currency — all within Indian sovereign territory but outside India’s domestic regulatory perimeter. Yet most commentary on GIFT City remains trapped in two registers: promotional material that reads like a brochure, or sceptical analysis that treats IFSC incentives as too good to be true. Neither register is useful. What is useful is a precise, provision-by-provision examination of what the law actually says — and what it means for the global asset management industry.
As an advocate practising at the Gujarat High Court and, serving as Senior Standing Counsel for the Income Tax Department, I have a professional interest in both sides of the tax architecture: the incentive framework that attracts capital, and the compliance framework that ensures those incentives are used within their intended boundaries. This article examines both.
The Twenty-Year Holiday: Section 147 of the Income-tax Act, 2025
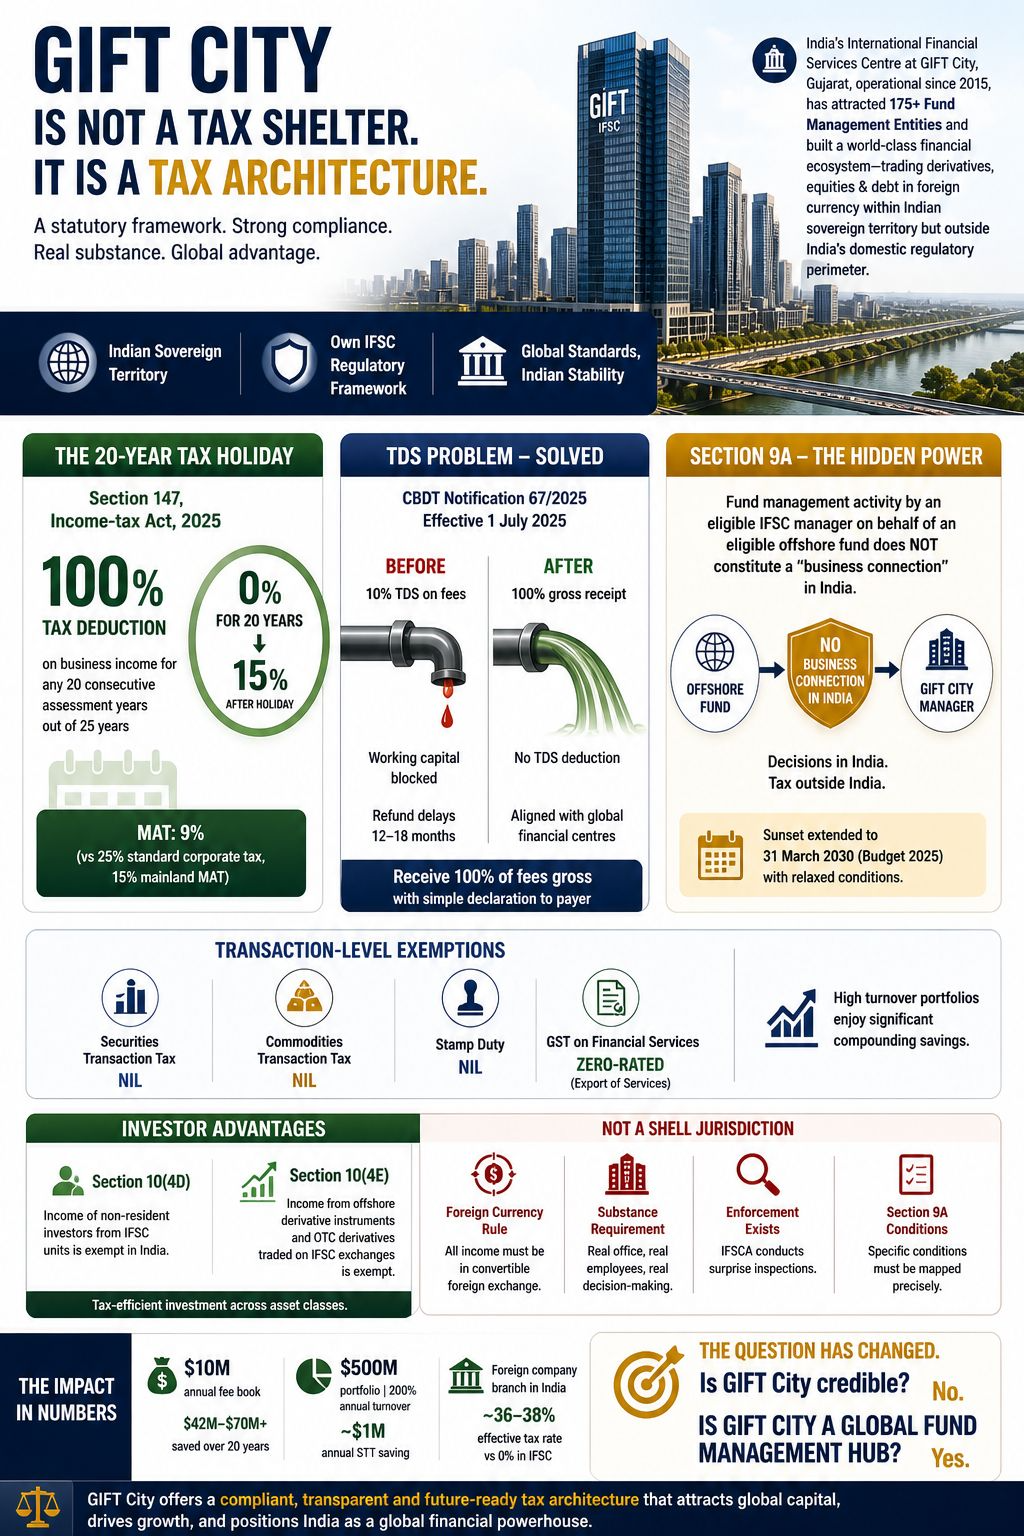
The headline incentive is now enacted law. Following Presidential assent to the Finance Act 2026 on 30 March 2026, Section 147 of the Income-tax Act, 2025 provides IFSC units a 100% deduction on business income for any 20 consecutive assessment years out of a block of 25 years. After the holiday period, a concessional rate of 15% applies. Minimum Alternative Tax for IFSC units is 9% — roughly one-third of the standard 25% corporate tax rate, and well below the 15% mainland MAT. This is not a proposal or a budget announcement. It is law, effective 1 April 2026.
For a Fund Management Entity operating a Portfolio Management Service from GIFT City, this means every dollar of management fee, performance fee, and advisory fee collected in convertible foreign exchange is tax-free for two decades. The saving is substantial regardless of which baseline you choose. Against the US federal rate of 21%, a USD 10 million annual fee book saves approximately USD 2.1 million per year — USD 42 million over the holiday. Against the UK’s 25% rate, USD 50 million. And for a foreign company operating through a branch in India — which would otherwise face an effective Indian tax rate of approximately 36–38% (at the base rate of 35% effective from FY 2024-25, plus surcharge of 2–5% and 4% health and education cess) — the saving is approximately USD 3.7 million per year, or over USD 70 million over two decades. The GIFT City incentive does not merely match competing financial centres; on the arithmetic of enacted legislation, it exceeds them.
The TDS Problem — Solved: CBDT Notification 67/2025
Until June 2025, GIFT City FMEs faced a persistent cash-flow irritant: 10% tax deduction at source on every fee payment received, requiring annual refund claims with 12–18 month processing cycles. CBDT Notification No. 67/2025, dated 20 June 2025 and effective 1 July 2025, eliminated this entirely. FMEs — including PMS operators, AIFs, and mutual fund companies — now receive 100% of their fees gross, provided they furnish a statement-cum-declaration in the prescribed form to each fee payer. This is a compliance calendar item, not a structural burden. It aligns GIFT City’s cash-flow position with Singapore, Hong Kong, and Dublin.
The Provision Nobody Reads: Section 9A
Section 9A of the Income-tax Act is, in my assessment, the most commercially transformative provision in India’s IFSC framework — and the least discussed in asset management circles. It provides that fund management activity carried out through an eligible IFSC-based fund manager on behalf of an eligible offshore fund does not constitute a “business connection” in India for that offshore fund. The consequence: the offshore fund pays zero Indian tax, even though investment decisions are made from Indian soil.
Budget 2025 extended the Section 9A sunset to 31 March 2030 and relaxed several conditions for IFSC-based managers. The practical implication is striking. A GIFT City Principal Officer — the same individual who satisfies IFSCA’s substance requirements under Regulation 7(7) of the Fund Management Regulations 2025 for Indian PMS clients — can simultaneously make investment decisions for the firm’s offshore fund vehicles without those vehicles acquiring Indian tax liability. One office, one set of key managerial personnel, serving both Indian resident clients and global offshore portfolios. The “minimum viable” GIFT City operation that global managers reluctantly contemplate as a regulatory overhead is, properly structured, a regional fund management hub at zero tax.
I emphasise the caveat: Section 9A has specific conditions relating to fund corpus, investor diversification, and manager remuneration. These must be mapped with precision by qualified tax counsel. But the directional intent is unmistakable — India wants IFSC-based managers to manage global capital.
Transaction-Level Exemptions: The Compounding Effect
Beyond the entity-level tax holiday, GIFT City eliminates transaction-level friction that compounds across an actively managed portfolio. Securities Transaction Tax: nil. Commodities Transaction Tax: nil. Stamp duty: nil. GST on financial services: zero-rated as export of services. For a USD 500 million portfolio with 200% annual turnover, the STT saving alone — at the equity delivery rate of 0.1% — is approximately USD 1 million per year. These are not headline numbers, but for an operations team modelling total cost of ownership, they shift the calculus.
Non-resident investors benefit additionally from Section 10(4D), which exempts income of specified IFSC funds — including Category-III AIFs — from Indian tax to the extent attributable to non-resident unitholders. Section 10(4E), as amended by Finance Act 2025, extends this to OTC derivatives and offshore derivative instruments transacted through IFSC banking units. For portfolio managers whose strategies employ derivative overlays, this is a genuine expansion of the tax-efficient investment universe.
The Compliance Architecture: What the Incentive Framework Demands
Every incentive has a compliance condition. The conditions here are real and must not be minimised in any honest assessment.
First, the foreign-currency requirement: Section 80LA (now Section 147) mandates that the income must be received in convertible foreign exchange. All management fees must be invoiced and collected in USD, EUR, or GBP through IFSC Banking Units. Indian resident clients remitting under the Liberalised Remittance Scheme do so in foreign currency, so the condition is organically satisfied for PMS — but the banking and documentation architecture must be structured from Day 1.
Second, substance: IFSCA’s Fund Management Regulations 2025 require that the “proposal on the portfolio composition shall be initiated by a person who is based in the office of the FME in the IFSC.” This is not a formality. On 2 May 2025, IFSCA issued its first enforcement action on substance — a formal warning to an FME whose key managerial personnel were not physically present during unannounced surprise visits. The message is clear: GIFT City is not a brass-plate jurisdiction. If you claim the tax holiday, you must have real people making real decisions from a real office in GIFT SEZ.
Third, Section 9A conditions: the safe harbour is not a blank cheque. Fund corpus limits, investor diversification requirements, and remuneration thresholds must be individually mapped. A global manager who assumes Section 9A compliance based on a pitch deck rather than a provision-by-provision analysis is building on sand.
The Structural Argument
The distinction between a tax shelter and a tax architecture is not semantic. A shelter is a structure designed to avoid tax that would otherwise be payable, typically through treaty arbitrage or artificial arrangements. GIFT City is the opposite: it is a sovereign statutory framework — enacted by Parliament, gazetted by the Central Board of Direct Taxes, and enforced by the IFSCA — that creates genuine incentives for genuine operations. The incentives are large. The conditions are real. And the compliance infrastructure — from IFSCA’s unannounced inspections to the foreign-currency requirement to the substance test — is designed to ensure that only entities with real operations in GIFT City benefit.
For the global asset management industry, the strategic question is no longer whether GIFT City’s incentives are credible. They are enacted law. The question is whether global managers will evaluate GIFT City as a cost to bear for Indian market access — or as a platform to leverage for tax-efficient global fund management. The law supports the second reading. The numbers demand it.
About the Author: Advocate Aaditya Bhatt is the Senior Partner at Bhatt & Joshi Associates, a law firm established in 1978 and based in Ahmedabad. He practices at the Gujarat High Court and has served as Senior Standing Counsel for the Income Tax Department. He holds a B.E. from L.D. College of Engineering and an LL.B. from Sir L.A. Shah Law College. BJA’s practice spans tax litigation, corporate disputes, arbitration, banking law, admiralty law, GIFT City/IFSC advisory, white collar crimes amongst other areas of law..
Disclaimer: The views expressed are personal and do not represent the views of the Income Tax Department or any government authority. This article is for informational purposes and does not constitute legal or tax advice.